Digital Financial Planning Invitation

Plan Today.
Live Tomorrow With Confidence.

Financial planning isn't about choosing a product. It's about preparing for the things that matter to you.
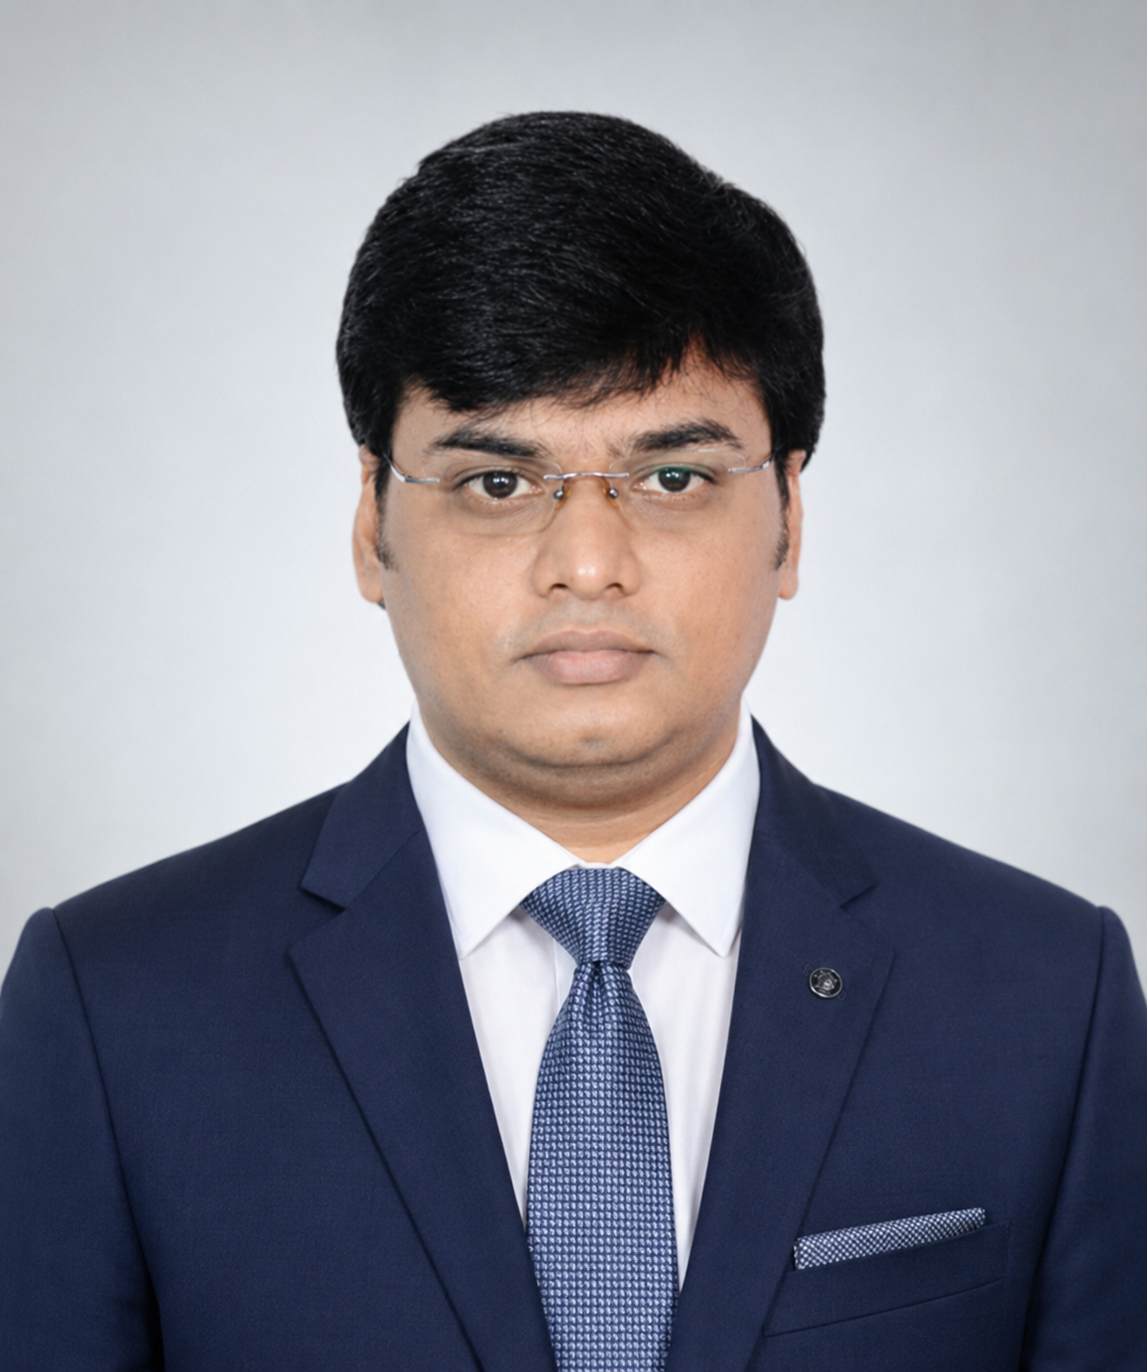
About Madan LJ
Take a few minutes. Explore what matters to you.
Madan LJ - Financial Planner

Madan LJ

Fiduciary Financial Strategist
WhatsApp Verified Direct Desk
"True wealth management begins with your family's personal goals—free from corporate sales pressure."
15+
Years Advisory
100%
Unbiased Plan
₹500Cr+
Guided Assets

What Would You Like To Plan For?

Select a financial goal below to watch an essential 60–90 second educational video, audit your preparedness, and connect on WhatsApp.

Retirement

Build Your Financial Independence

Understand how much you may need to maintain the lifestyle you want after your working years.

90s Educational Video • Self-Assessment
Explore Retirement
Children

Plan For Tomorrow's Dreams

Turn education and other important future goals into a structured financial plan.

75s Educational Briefing • Inflation Forecaster
Explore Children's Future
Protection

Protect What Matters Most

Understand how financial protection can help your family continue its journey even when life takes an unexpected turn.

80s Strategic Briefing • Adequacy Audit
Explore Protection
Healthcare

Prepare For The Unexpected

Review whether your current health insurance protection is aligned with your family's needs.

70s Healthcare Briefing • Room-Rent Check
Explore Health Protection
All Goals / Retirement Planning
RETIREMENT PLANNING
"For Your Proud Retirement"

Your Salary May Stop One Day.
Your Lifestyle Doesn't Have To.

Retirement isn't an age; it is a financial number. Watch this 90-second advisory briefing to understand why traditional savings fall short against 30 years of post-retirement inflation.

How Much Will You Actually Need For Retirement?
90-Second Fiduciary Briefing
0:00 / 1:30
Key Topics Addressed In This Briefing
Inflation Lifestyle expenses Healthcare Longevity Retirement corpus Existing investments Starting early Regular investing Periodic review

Retirement Corpus Gap Estimator

See how 6% annual inflation impacts your living costs over a 25-30 year retirement horizon.

Your Current Age: 32 Yrs
Current Monthly Expenses: ₹1,00,000
Projected Corpus Needed At 60
₹12.5 Cr
Future Monthly Living Cost: ₹5,03,000/mo

Key Takeaways

"Your retirement requirement is unique to you."

01 / LONGEVITY REALITY

The 30-Year Cashflow Challenge

With advancing medical longevity, you may live 30+ years without an active salary. Fixed deposits cannot withstand sustained inflation without capital erosion.

02 / THE 6% INFLATION DRAIN

Compounding Living Costs

At 6% inflation, a ₹1 Lakh monthly budget swells to ₹3.2 Lakhs in 20 years. Your portfolio must balance equity growth with capital stability.

03 / BESPOKE ALLOCATION

Integrating Existing Assets

EPF, NPS, real estate, and equity investments must be audited as one cohesive cashflow engine, not isolated products.

Ready to map your retirement timeline?

Start a direct, confidential WhatsApp consultation with Madan LJ.

How Prepared Are You?

Answer 3 quick questions to evaluate your retirement readiness.

1
Have you calculated your retirement requirement?
2
Do you know how inflation could affect your future expenses?
3
Are your current investments aligned with your retirement goal?
All Goals / Children's Future
CHILDREN'S FUTURE PLANNING

Today's Small Decisions Can Shape Tomorrow's Opportunities.

Higher education inflation in India runs at 10-12%—twice the rate of standard retail inflation. Structured planning ensures your child has unbounded options without exhausting your retirement funds.

Topic 1 of 5 75s Briefing

The 10-12% Education Inflation Curve

In India, higher education costs double every 6 to 7 years—far outpacing ordinary CPI inflation.

₹25L today = ₹87L in 13 years
Planning Tomorrow's Opportunities Today
75-Second Educational Presentation
0:00 / 1:15
Key Topics Addressed In This Briefing
Education inflation Higher education Post-graduation Future goals Time horizon Goal amount Investment planning Periodic review

Higher Education Inflation Forecaster

Calculate future college costs assuming a conservative 10% annual education inflation rate.

Child's Current Age: 5 Yrs (13 yrs to college)
Today's Cost of Degree: ₹25 Lakhs
Estimated Future Requirement
₹86 Lakhs
Inflation-adjusted target when your child turns 18.

Key Takeaways

"Your child's future requirement is unique to their personal aspirations."

01 / TIME HORIZON POWER

The Early Start Compounding Advantage

Starting structured investments when your child is in primary school allows equity compounding to fund the lion's share of tuition.

02 / DE-RISKING MANDATE

The 3-Year Glidepath Strategy

Never leave college fees in volatile equities right before admissions. Systematically de-risk into high-safety debt instruments 3 years prior.

03 / RING-FENCED ASSETS

Avoid Retirement Capital Raids

A segregated children's fund prevents parents from sacrificing their own old-age financial independence or taking high-interest loans.

Structure a dedicated roadmap for your child

Discuss goal milestones and tax-efficient portfolio design directly with Madan LJ.

How Prepared Are You?

Evaluate your child's educational financial plan.

1
Have you calculated the inflation-adjusted cost of your child's higher education?
2
Do you have a dedicated investment portfolio segregated for your child's milestones?
3
Is your child's educational roadmap protected against unexpected life events?
All Goals / Family Protection
FAMILY PROTECTION

If Your Income Stops Tomorrow, What Happens To Your Family's Financial Plan?

Pure term insurance is not an investment; it is an income replacement mechanism. Learn how to calculate adequate cover to insulate your home loan, family living expenses, and children's aspirations.

Topic 1 of 5 80s Briefing

Income Replacement: The Core Purpose

Pure term insurance is not an investment. Its sole purpose is to replace 15 to 20 years of your household income.

Maintain family lifestyle uninterrupted
Protecting What Matters Most: Pure Protection Strategy
80-Second Strategic Briefing
0:00 / 1:20
Key Topics Addressed In This Briefing
Income replacement Home loans Existing liabilities Children's education Family expenses Existing life insurance Protection adequacy Pure protection

Term Protection Adequacy Benchmark

Based on Indian wealth management guidelines: 20x annual income + 100% of outstanding debt.

Your Annual Gross Income: ₹25 Lakhs/yr
Outstanding Loans & Liabilities: ₹50 Lakhs
Recommended Pure Life Cover
₹5.50 Cr
Ensures debt clearance + 20 years uninterrupted household cashflow.

Key Takeaways

"Your family's protection must match your true economic value, not a random policy size."

01 / THE 20X MULTIPLIER RULE

Income Replacement Science

Your life cover must equal at least 15 to 20 times your annual earnings plus debt. A ₹50 Lakh policy for a ₹20 Lakh earner provides barely 2.5 years of protection.

02 / ENDOWMENT MIS-SELLING

Separate Insurance from Investing

Traditional endowment and money-back plans yield 4-5% while charging steep premiums for tiny cover. Pure term gives multi-crore peace of mind at minimal expense.

03 / LEGAL SAFEGUARD (MWPA)

Married Women's Property Act

Registering your term cover under the MWP Act guarantees that the claim proceeds are legally ring-fenced for your wife and children, untouched by creditors.

Is your existing life cover truly adequate?

Request an unbiased fiduciary audit of your current policies on WhatsApp.

How Prepared Are You?

Audit your family's financial security.

1
Does your existing life cover equal at least 15 to 20 times your annual income?
2
Are your outstanding loans and liabilities factored into your current life cover?
3
Is your cover held in pure term insurance rather than low-yield endowment policies?
All Goals / Health Protection
HEALTH PROTECTION

Can Your Current Health Cover Handle Tomorrow's Medical Costs?

With 14% annual medical inflation in private Indian hospitals, a basic ₹5 Lakh policy or corporate group cover can leave your family severely exposed. Discover how Super Top-ups and zero-room-rent policies protect your wealth.

Topic 1 of 5 70s Briefing

14% Healthcare Inflation Reality

Private healthcare costs in tier-1 Indian metros are skyrocketing. Standard ₹5 Lakh policies are quickly exhausted.

Critical care treatments exceed ₹25L–₹40L
Healthcare Inflation & Comprehensive Medical Defense
70-Second Healthcare Briefing
0:00 / 1:10
Key Topics Addressed In This Briefing
Medical inflation Current sum insured Family members Employer insurance Waiting periods Room-rent limits Additional cover Policy review

Key Takeaways

"Your health insurance must be independent of your employer and free from restrictive sub-limits."

01 / THE EMPLOYER ILLUSION

Corporate Cover Is Temporary

Corporate group coverage ceases the moment you transition jobs, face downsizing, or retire. Acquiring personal retail cover later in life triggers waiting periods and medical tests.

02 / ROOM-RENT TRAP

Proportionate Deductions

If your policy caps room rent to 1% of sum insured (e.g. ₹5,000/day), choosing a ₹10,000 room allows the insurer to slash up to 50% across surgeon fees and OT charges.

03 / SUPER TOP-UP LEVERAGE

₹50L Protection At Low Cost

By structuring a ₹5 Lakh base health plan with a ₹45 Lakh Super Top-up (with a ₹5L deductible), you secure high-grade protection for a small incremental premium.

Protect your savings from sudden hospitalization

Have Madan LJ audit your room-rent limits, restoration clauses, and family coverage.

How Prepared Are You?

Check the resilience of your family's health cover.

1
Do you rely solely on your employer-provided health insurance?
2
Does your health insurance policy have sub-limits or room-rent restrictions?
3
Have you reviewed if your sum insured can absorb treatments costing ₹25L–₹50L?
Madan LJ - Fiduciary Wealth Strategist
15+
Years Advisory Experience

Madan LJ

Founder & Chief Wealth Strategist | Investment Planning & Risk Management

With over 15 years of personalized advisory experience, Madan LJ has helped hundreds of Indian working professionals, IT executives, business founders, and families build generational financial independence and unshakeable risk protection.

Unlike product-distribution networks driven by corporate sales quotas, Madan's advisory approach is rooted in fiduciary discipline: understanding your life goals first, stress-testing against inflation and life risks, and curating an objective roadmap.

Fiduciary Mindset

Zero bias. Planning first, products never first.

WhatsApp-First Access

Direct 1-on-1 access. No call centers or junior reps.

Goal-Driven Architecture

Seamlessly synchronizing retirement, education, and protection.

Periodic Reviews

Systematic rebalancing to safeguard against life transitions.

Start A WhatsApp Advisory Conversation

Personal financial planning is private. There are no cold web forms, no telemarketing calls, and no spam. Connect directly with Madan LJ for a warm, confidential review of your personal finances.

100% Confidential 1-on-1 dialogue with Madan LJ
Review retirement corpus gaps, education roadmaps, and insurance coverage
No product selling bias — pure financial planning focus

Direct WhatsApp Desk

Tap below to start a private conversation with Madan LJ.

Open WhatsApp Now
Madan LJ
Madan LJ Online
Advisory Conversion & Analytics Monitor
0
Category Views
0
CTA Clicks
0
Assessments
0
WhatsApp Leads
Real-time Client Journey Event Log:
Connecting to WhatsApp...